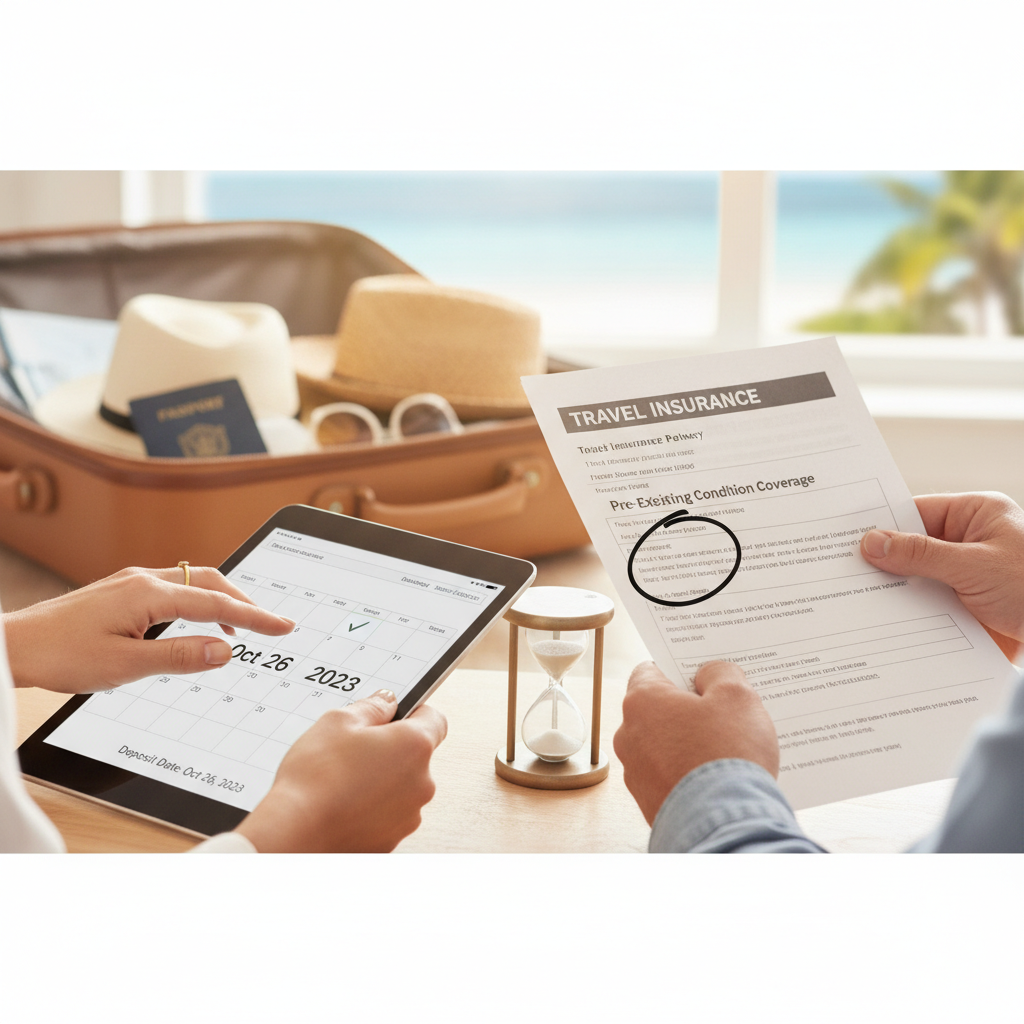
Most travelers buy insurance the week before departure — and quietly leave some of the most valuable coverage on the table without realizing it. The 14-day window that opens from the moment you make your first trip deposit isn't a marketing footnote. It's a structural feature of most comprehensive travel insurance policies, and what you gain by acting within that window can mean the difference between a policy that covers your reality and one that excludes the parts of your health history most likely to matter.
Understand Why the Timing Window Exists at All
Travel insurance providers use the 14-day window to limit adverse selection — the tendency for people to buy coverage only once a medical situation or trip disruption becomes likely. When you purchase within the defined period after your first deposit, the insurer treats that as good-faith enrollment before anything significant has changed. In exchange, they extend coverage for pre-existing medical conditions, time-sensitive cancellation triggers, and in some cases, financial default protection for travel suppliers. Waiting past that window signals a different risk profile, and the policy adjusts accordingly by excluding those elements.
What Pre-Existing Condition Coverage Actually Means
A pre-existing condition, for insurance purposes, is any illness, injury, or medical event for which you sought treatment, received a diagnosis, or had symptoms during a defined lookback period — often 60 to 180 days before purchase. Without the early purchase benefit, a claim related to that condition is almost always denied. With it, the same claim may be covered in full, provided the policy's other conditions are met, such as being medically stable at the time of purchase.
This matters far more than most travelers anticipate. A managed chronic condition — controlled blood pressure, a previous cardiac event, a history of respiratory illness — becomes a policy gap the moment you wait too long to buy. Platforms like **InsureMyTrip** and **Squaremouth** let you filter policies by whether they include a pre-existing condition waiver and specify how many days from initial deposit you have to qualify. Checking both sites side by side gives you a clear read on which plans preserve that window.
The First Deposit Rule and How to Apply It Correctly
The clock starts with your first payment toward any part of the trip — not the final booking, not the last payment on a payment plan. If you put down a deposit on a cruise package through a provider like **Viking** or **Regent Seven Seas** in January, your 14-day window runs from that date, regardless of when the final balance is due or when you book connecting flights. Missing this is the most common mistake travelers make. They book the cruise, assume the insurance purchase can wait until the flight is confirmed, and then find themselves outside the window with a policy that won't honor the waiver.
To apply it correctly: the moment any money changes hands toward a trip, that day is day one. Many financial advisors and travel specialists recommend setting a calendar reminder for day 13 as a hard deadline for completing the insurance purchase.
Cancel for Any Reason Is Also Time-Sensitive
Cancel for Any Reason — commonly abbreviated CFAR — is a policy upgrade that allows you to cancel a trip for any reason not otherwise covered and receive a partial reimbursement, typically around 75% of non-refundable costs. It's the only real protection against changing your mind, family circumstances shifting, or simply deciding a trip no longer makes sense. CFAR upgrades almost universally require purchase within the same 14-day window as the pre-existing condition waiver.
Without early enrollment, CFAR is simply unavailable as an add-on. That removes what many travelers consider the most flexible and practical layer of protection — particularly valuable for expensive international trips or bookings made a year or more in advance. Tools like **Travel Guard** allow you to price CFAR as part of the base policy comparison before committing, so you can see the full cost difference upfront.
How to Shop Smart Within the Window
The 14-day rule creates a natural urgency, but it shouldn't push you toward a hasty decision. Most reputable comparison platforms allow you to generate and review quotes in under ten minutes. The key variables to compare aren't just price — they're the lookback period for pre-existing conditions, the definition of medical stability, trip interruption limits, and emergency evacuation coverage.
For any trip involving non-refundable air, international accommodations, or travelers with ongoing health management needs, comprehensive coverage purchased early will almost always cost less than a single denied claim. The early purchase window exists to reward exactly this kind of forward planning, and using it consistently is one of the more reliable ways to get genuine value from travel insurance rather than simply the appearance of it.
Acting within the 14-day window after your first deposit is the single most reliable way to ensure your travel insurance reflects your actual circumstances — including your health history, your cancellation flexibility, and the full non-refundable value of your trip. The coverage that disappears when you wait isn't incidental fine print; it's the coverage most likely to matter when something actually goes wrong. As you start mapping out your next trip, booking the insurance alongside that first deposit is worth treating as part of the trip-planning process itself.