Most people with solid financial habits still find themselves stuck in the same frustrating moment: a genuinely great deal appears — a flash sale on a piece of gear you've wanted, a limited-time flight window, a discounted annual subscription — and instead of acting, you hesitate. The money is technically there, but it's sitting in your emergency fund, and tapping that feels wrong. So the deal expires, or you charge it impulsively and feel guilty about it later. There's a cleaner way to handle this, and it doesn't require a bigger budget — just a smarter structure.
Understand Why the Emergency Fund Isn't the Problem
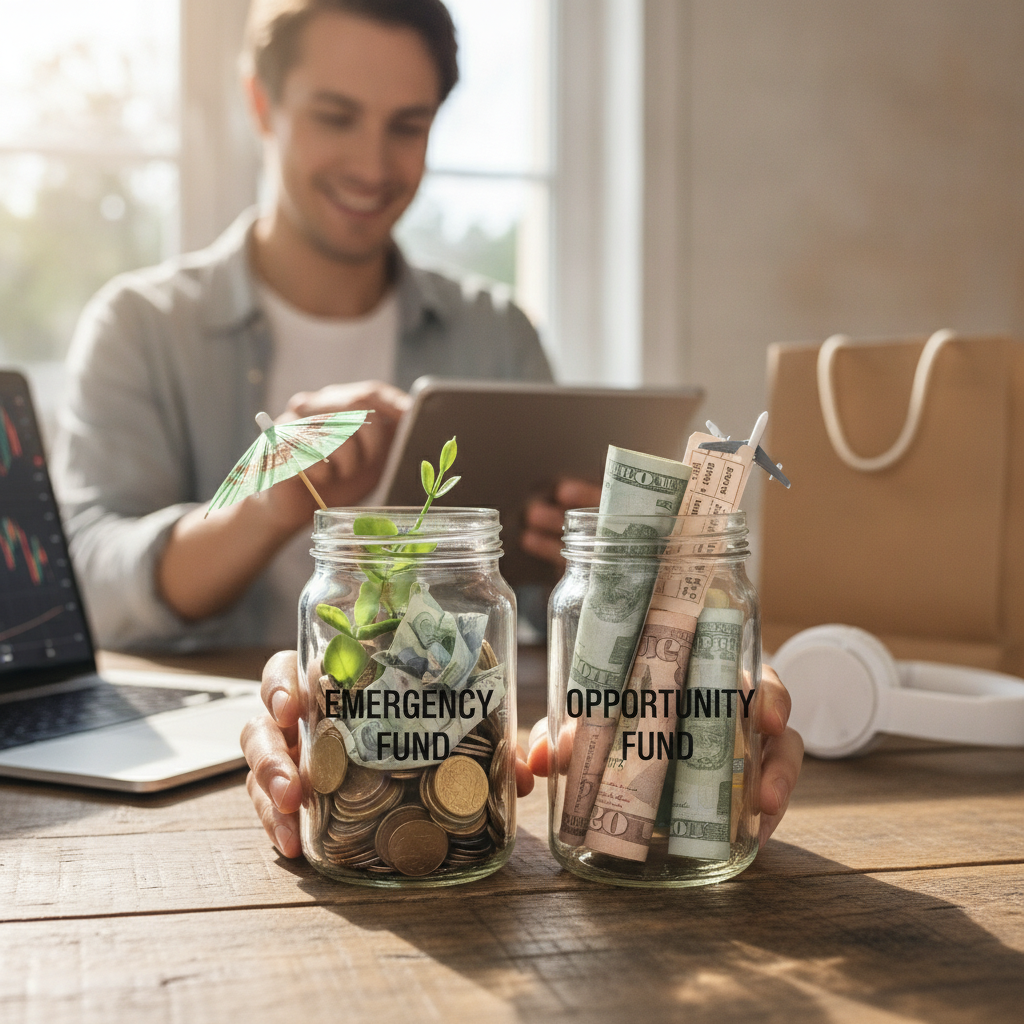
Your emergency fund exists for one purpose: absorbing genuine financial shocks without forcing you into debt. Job loss, a car repair, an unexpected medical bill — these are the events it's designed to cover. When you start treating that fund as a general-purpose backup for opportunity spending, you erode the psychological and practical safety net it provides. Even if you always replenish it, the habit of dipping in creates a slow leak in your financial confidence. Keeping that account strictly off-limits isn't excessive — it's the whole point.
Define What an Opportunity Fund Actually Is
An opportunity fund is a separate, smaller cash reserve set aside specifically for time-sensitive purchases that are genuinely worth acting on. Think of it as pre-approved discretionary spending that doesn't compete with your bills, your savings goals, or your emergency cushion. It's not a slush fund for impulse buys — it has a defined ceiling and a defined purpose. The distinction matters because it gives you a clear mental frame: if the deal qualifies and the funds are there, you can move confidently without second-guessing or guilt.
Set a Realistic Target Balance Before You Start
The right size for an opportunity fund depends on your lifestyle and the kinds of deals you realistically encounter. For most people, a modest balance is enough to cover a decent travel deal, a limited-time tech discount, or a bulk purchase of something you use regularly. The goal isn't to accumulate a large reserve — it's to have enough on hand that meaningful opportunities don't slip by while you scramble to figure out the logistics. Apps like YNAB or a dedicated bucket in a Marcus or Ally high-yield savings account work well for this because they let you label the money clearly and keep it visually separate from other goals.
Open a Physically Separate Account for This Purpose
Keeping the opportunity fund in the same account as your emergency savings defeats the purpose. When money is pooled together, the mental boundary blurs quickly, especially during a moment of excitement when a good deal surfaces. A separate high-yield savings account — even one you open specifically for this at SoFi or Capital One — creates real friction between your funds. That friction is a feature, not a bug. It forces a brief pause before any transfer, which is enough to distinguish a genuine opportunity from an impulse purchase dressed up as one.
Build the Fund Gradually Without Stressing Your Budget
You don't need to fund this account all at once. A small automatic transfer each month — whatever fits comfortably without affecting your core obligations — builds the balance steadily. Some people seed it with a portion of a tax refund, a small bonus, or proceeds from selling items they no longer use. The key is treating contributions as consistent rather than sporadic. Once the account reaches your target ceiling, you stop contributing until you draw it down. This keeps the fund functional without letting it grow into a secondary savings account that you stop thinking about.
Create Simple Rules That Qualify a Deal as Worth Acting On
Without criteria, an opportunity fund can quietly become a justification engine for any purchase you feel excited about. A few simple filters help keep it honest. Ask whether the discount is meaningful compared to the normal price, whether you would have eventually bought this anyway, and whether the time pressure is real or manufactured by the seller. Retailers like Amazon and Best Buy regularly run "limited-time" promotions that recur weekly — those don't qualify. A genuine deal on a flight window that closes in 48 hours, a clearance event with actual inventory constraints, or a software bundle that won't be offered again — those are the scenarios this fund is designed for.
Replenish the Fund After Every Draw
Every time you pull from the opportunity fund, treat rebuilding it as a near-term priority. This doesn't mean it has to be urgent — just intentional. Adjust your next month's contribution slightly upward, redirect a small windfall, or temporarily pause a lower-priority subscription to recover the balance faster. The fund only remains useful if it's regularly refreshed. A depleted opportunity fund that never gets replenished is just a one-time permission slip, not a structural advantage. The real value is having the capacity available consistently over time.
Keep the Two Accounts Easy to Distinguish at a Glance
Labeling is underrated as a budgeting tool. Naming your emergency fund something concrete — "Emergency: 4 Months" — and naming your opportunity fund something equally specific — "Deal Fund" or "Move Fast Money" — makes the distinction visceral every time you check your accounts. Most online banks let you rename accounts freely, and this small step prevents the kind of fuzzy thinking that leads people to raid one bucket for purposes that belong to another. When the labels are clear, the mental accounting is easier, and decisions happen faster with less second-guessing.
As more people move toward goal-based banking — where every dollar has a label before it's spent — the opportunity fund concept is becoming a natural extension of that mindset. Financial tools are increasingly built around this kind of account bucketing, making it easier than ever to set up, automate, and monitor separate pools for specific purposes. The underlying principle is simple: financial stability and the ability to act quickly on real value aren't at odds with each other. You just need the right structure in place before the next great deal shows up.