Saving money is one of those things most people genuinely intend to do — but a vague commitment to "save more" rarely survives contact with an unexpected expense, a tempting sale, or a month where the numbers just don't cooperate. The problem often isn't willpower or income. It's that an unlabeled savings account feels like a shapeless pool of money with no clear identity, making it easy to justify pulling from it for almost anything.
Giving every savings account a name, a purpose, and a deadline changes that completely. What was once a passive balance becomes an active countdown — and that shift in framing has a surprisingly powerful effect on spending decisions day to day.
Name the Account After the Goal, Not the Category
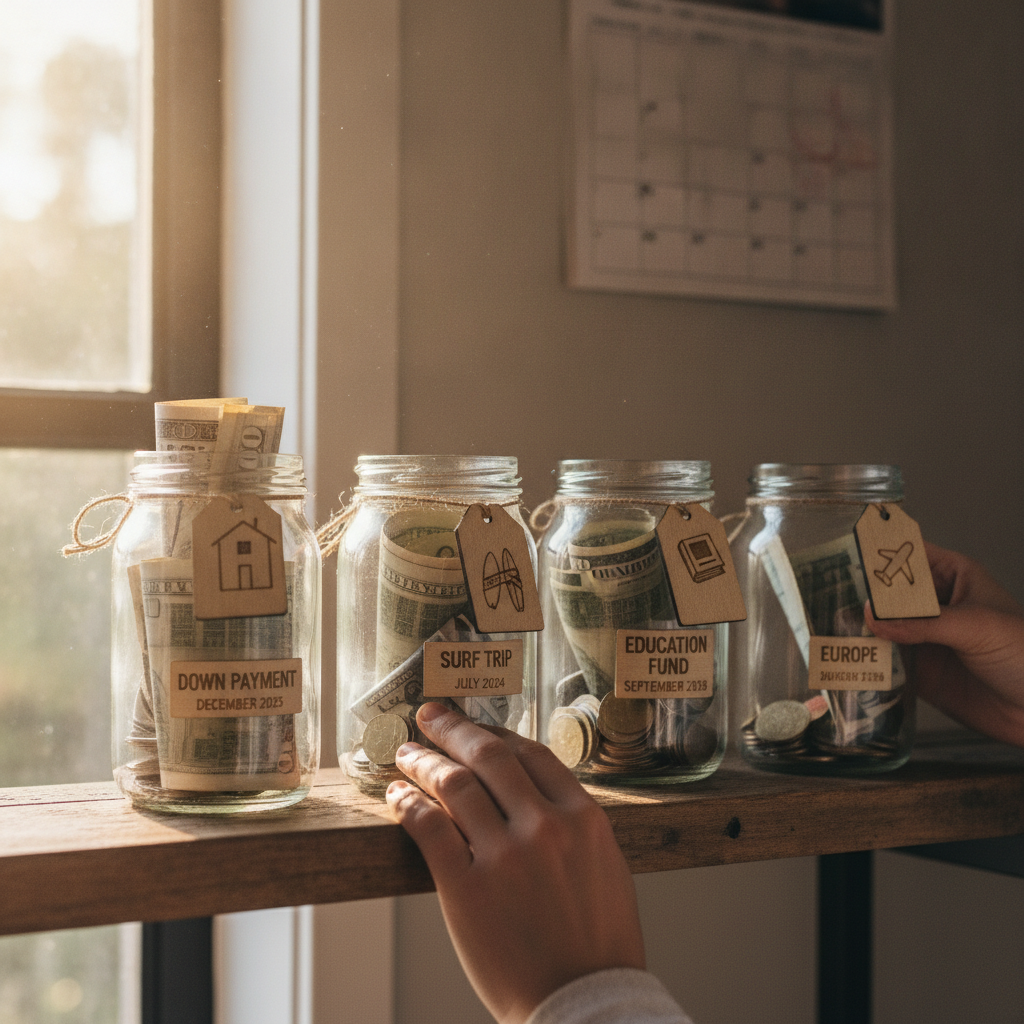
Most banks and credit unions — including online platforms like Ally, Marcus by Goldman Sachs, and SoFi — allow you to rename savings accounts or savings buckets with custom labels. Instead of calling an account "Savings 2" or leaving it as the default, rename it to something specific: "Japan Trip – October" or "New Laptop – March." The moment you see that label before a transfer, you're no longer moving money out of savings — you're taking from Japan. That specificity creates a small but real psychological barrier that vague account names never produce.
Set a Target Amount Before You Open the Account
A purpose without a number is still incomplete. Before you make the first deposit, calculate what the goal actually costs. Research flights, estimate accommodation, or price out the item you're saving toward. Then set that number as a fixed target inside your banking app — many platforms display a progress bar once you enter a goal amount. Watching a bar fill from 0% to 100% over several months turns an abstract financial habit into something that feels closer to a game with a finish line, which keeps motivation intact through slower months.
Assign a Realistic Target Date Based on the Math, Not Optimism
Once you have a target amount, divide it by the number of months between now and when you need the money. That figure is your required monthly contribution. If it's achievable, lock the date in. If it isn't, adjust the timeline rather than the standard — you're better off pushing the trip back two months than shorting the account and arriving underfunded. Apps like Qapital are built around exactly this structure, tying automated transfers to named goals with deadlines, so the math runs quietly in the background without requiring manual tracking each month.
Keep Each Goal in Its Own Separate Account
One of the most common mistakes is grouping multiple goals into a single savings account and tracking them mentally. Mental accounting is unreliable. When money sits in a single pool, the boundaries between goals blur, and it becomes easy to convince yourself that a partial withdrawal won't really affect the vacation fund because the emergency fund contribution was good this month. Keeping goals physically separated — one account per purpose — removes that ambiguity entirely. Each account has one job, and its balance tells you exactly where that goal stands.
Review Your Countdown Balances Weekly, Not Monthly
Monthly check-ins are too infrequent to catch a drift early. A quick weekly review — even just a two-minute glance at each labeled account — reinforces the connection between daily spending decisions and specific goals. If the "Home Office Upgrade" account is three weeks behind pace, you notice it while there's still time to adjust. If it's ahead of schedule, that's a small motivating win. Financial platforms like Betterment's cash management feature and YNAB both support goal-based account structures that make this kind of weekly review fast and clear.
Use the Label as a Decision Filter Before Discretionary Spending
Here's where the labeled account system earns its keep in a practical, everyday sense. Before any non-essential purchase, a quick mental check — "does this spending affect my countdown to [goal]?" — introduces a brief pause that impulse spending typically bypasses. It's not about guilt or restriction. It's about making the tradeoff visible. When the goal has a name and a date, the tradeoff between a spontaneous dinner out and a week's progress toward a home appliance replacement becomes concrete rather than theoretical, and that clarity is often enough to shift the decision.
Automate Transfers on Payday to Remove the Decision Entirely
The most reliable way to fund labeled accounts consistently is to make the transfer happen before the money touches your checking account. Set up automatic transfers — timed to your pay schedule — so each account receives its designated contribution the same day income arrives. This approach removes the weekly decision of whether to save or spend, which is where most savings plans quietly fall apart. When the transfer is automatic, the labeled balance grows on schedule regardless of how the rest of the month unfolds, and the countdown moves forward without requiring any deliberate effort.
---
Turning a savings balance into a named, dated goal doesn't require a complicated system or a new financial product. It requires naming what you're saving for, knowing what it costs, setting a date, and keeping each goal in its own dedicated account. That combination transforms saving from something you intend to do into something you can watch happen — one week, one transfer, one percentage point closer at a time. Start with just one account, one goal, and one target date, and see how different saving feels when it has somewhere specific to go.